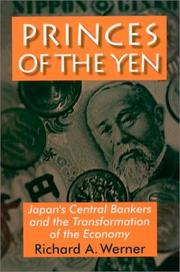
Princes of the Yen
A contested but influential reading of the Bank of Japan's credit guidance.
Summary
Richard Werner argues that the Bank of Japan, rather than fiscal policy or market forces, created the Japanese asset bubble of the late 1980s and then deliberately destroyed it in order to force structural change on the Japanese economy. This is a strong claim about intent, and the book is built to support it.
His mechanism is window guidance, the informal quota system through which the Bank of Japan told commercial banks how much to lend and to which sectors. Werner argues that the central bank directed enormous credit growth toward real estate and speculative lending during the 1980s, that this rather than interest rates drove the asset price rise, and that when the bank withdrew the guidance the bubble collapsed. He then argues that officials chose not to reflate during the 1990s because they wanted the crisis to break the postwar economic model, weaken the Ministry of Finance and force liberalisation.
Werner also develops his general theory that credit creation for asset purchases affects asset prices while credit creation for productive purposes affects the real economy, which is the basis of his later work on disaggregated credit. He is a heterodox economist and this thesis is not accepted by mainstream Japanese monetary historians, who attribute the bubble to a combination of financial liberalisation, the Plaza Accord's consequences and monetary policy errors without the deliberate intent Werner alleges. The evidence for intent is largely inferential and rests on interviews and on published statements. Read it as a serious heterodox argument that has not been accepted, and treat the intent claims separately from the credit analysis.
Key takeaways 7
- Werner argues that Bank of Japan window guidance, not interest rates, determined the volume and direction of Japanese bank lending in the 1980s.
- Credit created for asset purchases raises asset prices, while credit created for productive investment raises output, and aggregating the two conceals both.
- The withdrawal of lending guidance rather than the increase in interest rates ended the Japanese bubble.
- Werner alleges that Japanese monetary officials prolonged the 1990s stagnation deliberately in order to force structural change.
- Central bank independence transfers power to an institution that faces no electoral accountability for the outcomes it produces.
- Bank credit creation, rather than saving, is the source of new purchasing power in an economy.
- The intent claims rest on inference and are rejected by mainstream accounts of the Japanese bubble.
Who should read it
Investors interested in credit-driven asset cycles and in the disaggregated credit framework, treating the claims about deliberate policy intent as contested.
Where it sits in the reference 2
Similar books 6
Chosen by shared topics, the entries that hold them, and the people who recommended both.