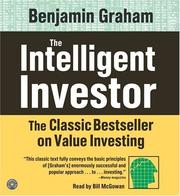
The Intelligent Investor
Revised through the 1973 fourth edition; 2003 Jason Zweig commentary edition.
Summary
Graham distinguishes investment from speculation and gives the defensive investor a set of rules that require no forecasting skill. An investment operation, in his definition, promises safety of principal and an adequate return on thorough analysis, and anything else is speculation. The book divides readers into defensive investors, who should hold a mechanical split between high-grade bonds and diversified large-cap stocks between twenty-five and seventy-five percent each, and enterprising investors, who may do more work in search of bargains.
Two ideas carry most of the weight. Mr Market is Graham's device for describing price quotations as offers from a manic-depressive partner, useful when he is irrational and ignorable otherwise. Margin of safety is the requirement that the purchase price sit far enough below appraised value that error and bad luck do not destroy capital. Graham applies both through explicit numerical criteria for earnings stability, dividend record, price to earnings and price to book.
Zweig's 2003 commentary sits after each chapter and does much of the practical work for a modern reader. He updates the examples to the dot-com bubble, converts Graham's specific screens into current terms, and argues for index funds as the default implementation of Graham's defensive strategy, which Graham himself moved toward late in life.
Much of Graham's own text is dated. His examples come from the 1930s to the early 1970s, the accounting conventions have changed, and quantitative screens of the type he specifies now find far fewer securities in developed markets. Book value means less in an economy dominated by intangible assets. Read chapters 8 and 20 on market fluctuations and margin of safety as the enduring core, and read the security selection chapters as historical method.
Key takeaways 8
- An investment operation must promise safety of principal and an adequate return on thorough analysis, and everything failing that test is speculation.
- The investor's chief problem, and worst enemy, is himself, because temperament determines results more than analysis does.
- Price quotations exist to serve the investor, not to inform him, so market prices should be used only when they offer an attractive transaction.
- Every purchase requires a margin of safety, meaning a price far enough below appraised value to absorb analytical error and bad luck.
- A defensive investor should hold a fixed allocation between high-grade bonds and diversified stocks and rebalance mechanically rather than forecast.
- Buying growth at high multiples exposes an investor to disappointment because the expected growth is already in the price and often fails to appear.
- Past performance of a security or fund provides almost no basis for expecting future performance.
- Most investors should accept market returns through a diversified low-cost holding rather than attempt an enterprising strategy they will not sustain.
Who should read it
Investors who want the origin of value investing in the author's own words, best read with Zweig's commentary and with the screening chapters treated as history.
About Benjamin Graham
Co-founder, Graham-Newman Corporation; lecturer in finance, Columbia Business School 1928-1956
Security Analysis and The Intelligent Investor are the founding texts of value investing and remain the primary source every later value investor argues from.
Where it sits in the reference 8
Who recommended it 28 · 14 direct
Similar books 6
Chosen by shared topics, the entries that hold them, and the people who recommended both.