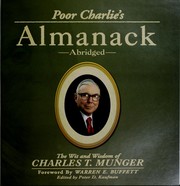
Poor Charlie's Almanack
Edited by Peter Kaufman; expanded Stripe Press edition published 2023.
Summary
The book collects Munger's speeches, talks and writings, edited by Peter Kaufman, with Munger's own commentary added. The centrepiece is the argument for a latticework of mental models drawn from many disciplines. Munger says that a person who knows only finance will force every problem into finance, and that competence requires the big ideas from psychology, mathematics, physics, biology, engineering and accounting held together well enough to be used.
The most cited section is The Psychology of Human Misjudgment, a talk that lists twenty-five standard causes of human error, including incentive-caused bias, liking and disliking distortion, doubt avoidance, inconsistency avoidance, deprival superreaction, social proof and what Munger calls lollapalooza effects, where several biases act at once in the same direction. He built the list from observation rather than from academic psychology, and he criticises academic psychology for not teaching the interactions.
The investing material argues for extreme concentration in a few understandable businesses bought at sensible prices, for inverting problems, for using checklists, and for staying inside a circle of competence with a clearly marked edge. Munger's talks on worldly wisdom in business include his account of how Coca-Cola could have been built from first principles, which is the clearest published example of his reasoning method.
The book has real limits. It repeats itself, because the speeches were given to different audiences over decades. Its editions are expensive and physically large, though a free authorised version now exists. Munger's psychology list is not a research literature and some items overlap or lack evidence. His investment advice presupposes a temperament and a capital base most readers do not have. It works best as a source of reasoning habits rather than as a method to copy.
Key takeaways 8
- A person needs eighty to ninety models from multiple disciplines to think competently, because a single discipline forces every problem into the wrong shape.
- Incentives explain more behaviour than intelligence or intention does, and anyone analysing a situation should identify who is paid for what before anything else.
- Inverting a problem, by asking what would guarantee failure and then avoiding it, solves questions that direct reasoning cannot.
- Several psychological biases acting together in the same direction produce effects far larger than the sum of the individual biases.
- Extreme concentration in a few well-understood businesses beats diversification for an investor who does the work.
- A great business bought at a fair price beats a fair business bought at a great price, which is the change Munger pushed Buffett to make.
- Knowing the boundary of your competence matters more than the size of that competence.
- Avoiding standard stupidities produces better lifetime results than pursuing brilliance.
Who should read it
Investors who want the reasoning method behind Berkshire's decisions, and anyone building a checklist for their own recurring errors.
About Charlie Munger
Vice-chairman, Berkshire Hathaway 1978-2023; chairman, Wesco Financial and Daily Journal Corporation
His latticework-of-mental-models talks reframed investing as applied multidisciplinary psychology and are quoted as a primary source across fields.
Where it sits in the reference 10
Who recommended it 28 · 9 direct
Similar books 6
Chosen by shared topics, the entries that hold them, and the people who recommended both.