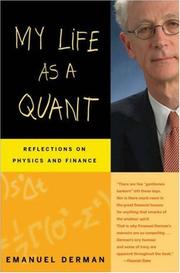
My Life as a Quant
Physicist to Goldman; the making of the volatility-surface era.
Summary
Derman, a theoretical physicist who moved to Wall Street in 1985, wrote a memoir of that transition and of the development of quantitative finance from inside Goldman Sachs.
The first part covers his training in particle theory at Columbia, the postdoctoral years, and the collapse of academic prospects in physics that pushed a generation of physicists into other fields. He is candid about the disappointment and about what it meant to leave a field he had trained for.
The finance sections describe specific work. He built the Black-Derman-Toy model with Fischer Black and Bill Toy, a one-factor interest rate model calibrated to the observed yield curve and volatility structure, which was among the first models usable for pricing bond options consistently with market prices. He worked on the volatility smile, the empirical fact that implied volatility varies with strike price in violation of the Black-Scholes assumption, and developed local volatility models with Iraj Kani that fit the observed surface. He describes the equity derivatives business and the relationship between the model builders and the traders who used the output.
The reflective material is what distinguishes the book. Derman argues that financial models differ fundamentally from physical ones: physics models describe a reality that does not know it is being modelled, while financial models describe human behaviour and are used by the people being described. He treats models as organised ways of thinking rather than as descriptions of truth, and argues that the profession's failure is treating them as the latter. He developed this further in Models Behaving Badly.
The book is a memoir and does not teach the mathematics. Its account of Goldman's internal culture is one participant's, and it stops well before the 2008 crisis.
Key takeaways 7
- Financial models describe human behaviour and are used by the people being described, which makes them fundamentally different from physical models.
- The volatility smile demonstrates that the Black-Scholes assumption of constant volatility is contradicted by observed market prices.
- A useful model is an organised way of thinking about a problem rather than a description of how the world works.
- The Black-Derman-Toy model was built to price bond options consistently with the observed yield curve rather than to describe interest rates.
- Quantitative finance was staffed by physicists because academic physics collapsed as a career path, not because the fields are similar.
- Traders use model output as one input among several, and the model builder's authority is limited to what the traders accept.
- Treating a calibrated model as a statement of truth rather than as an interpolation device is the profession's characteristic error.
Who should read it
Anyone working with quantitative models in finance who wants a practitioner's account of what the models actually are and what they cannot do.
About Emanuel Derman
Director of the financial engineering programme at Columbia University; earlier a physicist and head of quantitative strategies at Goldman Sachs.
My Life as a Quant describes how derivatives modelling was actually built on a trading floor, including the local volatility model Derman developed with Iraj Kani to fit the smile left after 1987. Models.Behaving.Badly states the limit of that work directly: financial models are approximations fitted to human behaviour, not physical laws, and treating them as laws is a specific way to lose money.
Similar books 6
Chosen by shared topics, the entries that hold them, and the people who recommended both.
A telecom analyst on the conflicts of interest in research during the 1990s bubble.

Fischer Black's life and ideas, from option pricing on, that shaped modern finance.
Recommended by: Mohnish Pabrai

Siegmund Warburg, who fled Germany and founded S.G. Warburg in London.
Recommended by: Mohnish Pabrai
Jamie Dimon's career and how JPMorgan Chase came through the 2008 crisis.
Life on Salomon Brothers' bond trading floor in the 1980s mortgage-bond boom.
“I do believe, as Michael Lewis writes in his intriguing 1989 book, "Liar's Poker," that it is unlikely that an individual unable to buck convention in one's life will suddenly be able to buck…” — Michael Burry
Source: MSN Money Strategy Lab journal, March 2, 2001 — archived
Recommended by: Michael Burry, Mohnish Pabrai, Nat Eliason and 3 others

A trader's memoir of Wall Street's after-hours world of drugs, sex and commissions.
Recommended by: Mohnish Pabrai
Where it sits in the reference 4
Topics