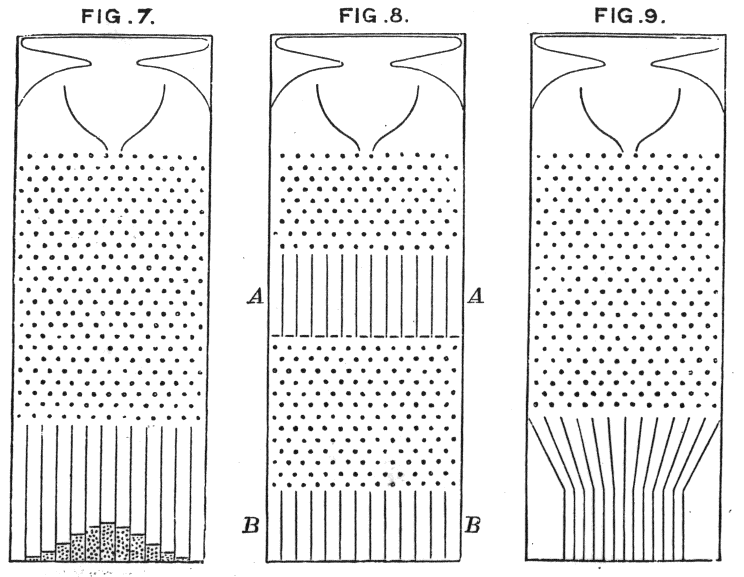
Regression to the Mean
Extreme results are part skill and part luck, and on the next draw the luck component resets, so outliers drift back toward average. Investors apply it by distrusting extrapolation: the fund on a hot streak, the company at record margins and the star analyst are each likelier to get worse than better. Where luck demonstrably drives the extreme, trimming after abnormal goodness is the model executed in one move.
5 books · 3 people behind it · 4 resources
Start here
- The Drunkard's WalkLeonard Mlodinow, 2008
- The Success EquationMichael J. Mauboussin, 2012
- Thinking, Fast and SlowDaniel Kahneman, 2011
The people behind it 3
Each person holds a book in this entry or names it in their own tags.
Investors 1
Academics 1

Journalists 1
Resources 4
- Regression to the MeanShane Parrish · essay · Why extremes drift back and forecasters misread it.
- Drawdowns and RecoveriesMichael J. Mauboussin · paper · Base rates for how deep declines end and rebound.
- Common Probability Errors to AvoidShane Parrish · essay · Small samples, base-rate neglect and the gambler's fallacy.
- Lucky vs. RepeatableMorgan Housel · essay · Separating skill from luck in a track record.
Books 5
Daniel Kahneman · 2011
Andrew WilkinsonCharles de VaulxFrank MartinMichael MauboussinMohnish PabraiRational Capital Investment FundSeth KlarmanStewart BrandAbi Tyas TunggalAlbert WengerAlfred LinAmy HoodBill GatesBryan JohnsonCharlie MungerDaniel BurkaDavid CancelDavid HellmannEv WilliamsJason FriedJason ZweigJulie ZhuoMarc AndreessenNassim Nicholas TalebNaval RavikantPaul BassatRay DalioRon ConwaySahil BloomSahil LavingiaSam AltmanSatya NadellaSophie BakalarTristan Harris

Michael J. Mauboussin · 2012