Updates

  1. Person pages list letters, writing, profiles and links as sortable tables with filters, and show each person's companies as links; Fund letters show each letter's description in its own column.
  2. Experts show a checked job title and a short description of each person; 30 more people have photographs.
  3. Every company, fund, university and publication the experts work for has a page listing the people there.
  4. Fund letters show each letter's thesis and filter by it; 225 person pages list the essays, columns and newsletter issues the person wrote.
  5. Person pages list every essay and newsletter issue a person wrote, and their own books as a table in List view.
  6. Recommends shows the five largest kinds of book and the rest under More; browse pictures load sooner.
  7. Podcasts and talks link the original episode, filter by Audio and video or Press, and list each publisher once.
  8. Pages are wider, Recommends has List and Grid, and a filter clicked again turns off.
  9. Book cards sit in a ruled grid with Open Library and Goodreads links and each book's one-line note.
  10. Funds is now Investors; each investor's styles are buttons that filter the table.
  11. Podcasts and talks on a person's page filter by year and publisher and show as a list or a grid of pictures.
  12. Quotes show only people's own words: 472 summaries written by list sites are gone.
  13. Country pages open from Browse again, and every link on the shelf lands on a page.
  14. Subject and person pages show their sections as tabs, and each book appears once on a person's page.
  15. Book cards show the quote, who said it and the source; grids show five cards to a row.
  16. On a phone, a menu holds the sections, search, Updates, Feedback and dark mode.
  17. Feedback takes a screenshot of the page with no browser prompt, opens a screenshot full size when you click it, and clears itself once sent.
  18. Book cards are centred, search names the topic each book sits in, and any text cut short shows whole on hover.
  19. Search groups its results by kind: people, companies, geographies, subjects, topics, books, funds, fund letters and papers.
  20. The Books table lists who recommended each book by name, and the browser tab names the section you are in.
  21. Feedback can take a screenshot of the page, or one you paste or choose, and opens in the corner beside Updates.
  22. Each rail button reopens its section where you left it, and Browse, Table and People show on every book and subject page.
  23. Filters grey out choices that hold nothing instead of hiding them, and Books › People filters by authors or recommenders.
  24. Feedback takes a subject line and up to three screenshots.
  25. Biographies are grouped by the person they are about: 41 new pages, from Abraham Lincoln to Lee Kuan Yew.
  26. Sport splits into 23 sports, and Religion into one topic per faith.
  27. Book lists show as cards: the cover, one recommendation quote and every recommender by name.
  28. Seventeen subjects that had two or three pages under different names now have one page each.
  29. Every page lists its Experts as authors and recommenders, with a link to them on the Experts tab.
  30. Economics, Financial history, Financial panics and Accounting are subjects of their own, with one page per financial crisis.
  31. Book, person and subject pages open inside the app, so the tabs stay in view.
  32. 996 more book covers, and photographs or logos for 227 more people and companies.
  33. Books › Browse shows every subject as cards, and the rail holds Fund letters, Papers, Experts, Books and Funds.
  34. Every topic over 150 books splits into narrower topics, each with a page of its own.

Send feedback

What is it?
Screenshots, up to 3 (optional)
or paste one with Ctrl+V

We use your email only to reply to you.

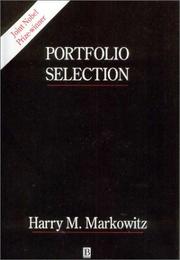
Portfolio Selection

Portfolio Selection

Harry M. Markowitz
1959
T1 351 pages · about 5h 51m to read Open Librarygoodreads

The original mean-variance monograph.

Summary

Harry Markowitz published the paper that founded modern portfolio theory in 1952 and this monograph in 1959, which develops the argument fully and supplies the computational method. It is the source document for how institutional portfolios are constructed.

The central insight is that an asset's contribution to a portfolio depends on its covariance with the other holdings rather than on its own risk and return alone. A security with high variance can reduce portfolio variance if it moves against the rest. From this Markowitz derives the efficient frontier: for each level of expected return there is a portfolio with minimum variance, and no rational investor should hold anything off that frontier. He supplies the critical line algorithm for computing the frontier under constraints, which was the practical contribution given the computing available in 1959.

The monograph also contains material the profession subsequently ignored. Markowitz discusses semi-variance, which measures only downside deviation, and states that it is the more appropriate risk measure but that variance is computationally tractable. He discusses the difficulty of estimating expected returns and covariances, which is the problem that has dominated practical application ever since, since optimisers amplify estimation error and produce concentrated portfolios. Later work on shrinkage estimation, resampling and Black-Litterman all address this. Markowitz himself later said he did not use mean-variance optimisation for his own retirement account. The framework remains the foundation of institutional practice.

Key takeaways 7

  1. A security's contribution to portfolio risk depends on its covariance with the other holdings rather than on its own variance.
  2. For each level of expected return there exists a minimum-variance portfolio, and the set of these forms the efficient frontier.
  3. Diversification reduces risk without reducing expected return, which makes it the only benefit available at no cost.
  4. Markowitz identified semi-variance as the more appropriate risk measure and used variance because it was computable.
  5. Mean-variance optimisation amplifies estimation error in expected returns, which produces concentrated and unstable portfolios.
  6. The critical line algorithm computes the efficient frontier under linear constraints, which made the theory usable in practice.
  7. Investors should be judged on portfolio outcomes rather than on individual security selection, because the interaction between holdings determines the result.

Who should read it

Investors and researchers who want the founding statement of diversification as a formal problem, including the caveats its author stated and the profession forgot.

Similar books 6

Chosen by shared topics, the entries that hold them, and the people who recommended both.
Peter L. Bernstein · 1992

How Markowitz, Sharpe, Fama, Black and Scholes built the theory of modern finance.

Lasse Heje Pedersen · 2015

Markets pay skilled active managers; a survey of the strategies they run.

Tony Robbins · 2014

Interviews with 50 investors, from Dalio to Bogle, turned into money advice.

“…books I've recommended, highlighted to death, or forced on friends.” — Andrew Wilkinson

Source: Andrew Wilkinson's Bookshelf, neverenough.com

Recommended by: Andrew Wilkinson, Nat Eliason, Ray Dalio and 1 other

Eugene F. Fama, John H. Cochrane, Tobias J. Moskowitz · 2017

Eugene Fama's key papers on efficient markets and asset pricing, with commentary.
William J. Bernstein · 2000

Modern portfolio theory for individual investors, explained without heavy maths.

Recommended by: The Barefoot Investor

Where it sits in the reference 1

Portfolio & risk

Topics

InvestingFinance and MarketsMathematics and StatisticsGames, gambling and quantitative finance