Games, gambling and quantitative finance
Books on game theory, betting systems, risk and fat tails, and the mathematics of markets, portfolios and derivatives.
Start here
- Theory of Games and Economic BehaviorJohn von Neumann, Oskar Morgenstern, 1944
- Portfolio SelectionHarry M. Markowitz, 1959
- The Strategy of ConflictThomas C. Schelling, 1960
- Beat the DealerEdward O. Thorp, 1962
- The Evolution of CooperationRobert Axelrod, 1984
The founding of game theory: expected utility and strategy among interacting players.
An asset's risk depends on how it moves with the rest of the portfolio.
Conflict as bargaining: commitment, credible threats and focal points.
Recommended by: Naval Ravikant
The first proven way to beat blackjack, by counting the cards left in the deck.
Computer tournaments of the prisoner's dilemma show why tit-for-tat wins.
Recommended by: Patrick Collison, Naval Ravikant
Game theory without maths: look forward, reason back, and make threats credible.
How people learned to measure risk, from early probability to portfolio theory.
“I think some of the books that are a must would be Peter Bernstein's book about risk, Against the Gods: The Remarkable Story of Risk.” — Charles de Vaulx
Source: De Vaulx naming Bernstein's book a must-read on risk
Recommended by: Charles de Vaulx, Jim Collins and 8 others

Stock, bond and bill returns for sixteen countries from 1900 to 2000.
Recommended by: Mohnish Pabrai
Von Neumann, game theory and the prisoner's dilemma in nuclear strategy.
Decades of US stock data testing which selection rules have beaten the market.
“Strongly Recommended. Great data.” — Mohnish Pabrai
Source: Mohnish's Bookshelf — Books on Investing & Capital Allocation, entry 336
Recommended by: Mohnish Pabrai, Patrick O'Shaughnessy
The Kelly criterion for sizing bets, from Bell Labs to casinos and hedge funds.
Recommended by: Mohnish Pabrai
Game theory without maths, with new examples: commitment, signals, bargaining.
The mathematics of risk parity: risk contributions and risk budgeting.

Power laws, scaling and critical points across physical and social systems
Recommended by: Nassim Nicholas Taleb
A mathematician's own losses used to explain market probability errors
Recommended by: Mohnish Pabrai
Edited volume of collected papers.
Recommended by: Nassim Nicholas Taleb
A risk manager's history of quantitative risk and what value-at-risk is for.

How physicists and mathematicians came to run money; useful context for Simons.
Recommended by: Eric Weinstein

The cross-sectional testing methods behind every factor claim.

Technical companion to the Incerto; free preprint on arXiv

Optimal-f and the practical arithmetic of fractional betting.

The technical reference on extreme value theory for insurance and finance
Recommended by: Nassim Nicholas Taleb
The statistical tools of empirical finance and the questions they test.

Log-periodic power laws as a physicist's model of crash formation
Recommended by: Nassim Nicholas Taleb

Compact mathematical treatment of derivative pricing and its applications
Recommended by: Nassim Nicholas Taleb
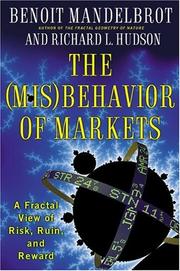
Why standard finance models understate market risk, from fractal geometry's creator.
Recommended by: Mohnish Pabrai, Nassim Nicholas Taleb and 1 other
A primer on the theory of games of strategy, written for non-specialists.
Recommended by: Naval Ravikant

 Andrew W. Lowrote 2 books here
 Nassim Nicholas Talebwrote 1 book here
 James P. O'Shaughnessywrote 1 book hereNassim Nicholas Talebrecommends 6 books here
 Mohnish Pabrairecommends 6 books here
 Naval Ravikantrecommends 3 books here
 Howard Marksrecommends 1 book here
 Jim Collinsrecommends 1 book here
 Marc Andreessenrecommends 1 book here
 Eric Weinsteinrecommends 1 book here
 Kevin Systromrecommends 1 book here
